Calculating Coverage Multipliers: Exactly How Much Life Insurance Do You Need?
Published by Andrew Benny | Content & Editorial Lead
Last updated: October 16, 2026
1. The Problem with Generic Multipliers
For decades, retail financial advice has leaned on a single simplified heuristic: buy 10 times your annual gross salary. If you earn $80,000 per year, purchase $800,000 in term life insurance coverage. While this heuristic is simple, it is fundamentally flawed. It ignores essential individual factors such as specific personal liabilities, existing household assets, family composition, interest rates, and long-term inflation dynamic trends.
A single income earner with three young children, a $400,000 mortgage, and zero liquid savings requires a vastly different risk management strategy than a dual-income household with a modest mortgage balance and significant brokerage accounts, even if both individuals share the exact same annual base salary.
Underestimating your required death benefit can leave remaining dependents financially exposed during critical years. Conversely, over-purchasing coverage drains discretionary capital through unnecessary premium payments funds that could otherwise be deployed toward tax-advantaged wealth creation, debt payoff, or emergency cash reserves.
2. Advanced Valuation Models Compared
Professional risk managers and quantitative financial planners utilize three distinct mathematical frameworks to establish ideal life insurance coverage targets. Understanding the underlying assumptions of each model enables you to choose the approach best suited to your household's financial architecture.
A. The Human Life Value (HLV) Model
The Human Life Value approach views an individual as an economic asset capable of generating net cash flows over time. It quantifies the net present value (NPV) of your future earned income dedicated to supporting dependents after accounting for taxes, personal consumption expenses, and self-maintenance costs.
The core mathematical formulation for HLV is as follows:
HLV Formula:
NPV = SUM [ (Gross Income - Personal Expenses - Taxes) / (1 + r)^t ]
Where r = net discount rate (investment yield minus wage growth), and t = remaining working years until target retirement age.
B. The Financial Needs Analysis (DIME Framework)
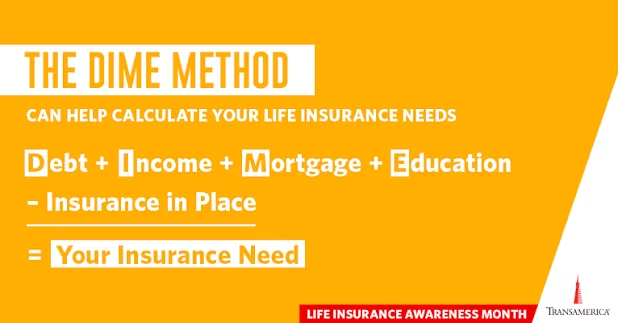
While HLV measures pure economic earning potential, the DIME methodology focuses directly on obligations and liabilities. This granular approach breaks down total financial liability into four distinct categories:
- Debt (D): The aggregate sum of all short- and medium-term non-mortgage liabilities. This includes consumer credit balances, personal lines of credit, automotive loans, student debt, and outstanding medical bills.
- Income (I): The total monetary income required to replace the wage earner's contributions for a specified duration (typically until the youngest dependent reaches economic independence, usually age 18 to 22).
- Mortgage (M): The total pay-off balance required to fully settle remaining real estate obligations, removing housing stress for surviving family members.
- Education (E): Projected future higher-education expenses for children, factoring in tuition inflation (historically running higher than core CPI).
C. The Capital Retention Method
The Capital Retention Method is the most conservative valuation framework. Instead of consuming the principal death benefit over time to cover living expenses, the principal amount remains untouched in an income-generating trust or conservative portfolio. Only the annual yield and dividends generated by the capital lump sum are distributed to meet living expenses.
3. Step-by-Step DIME Calculation Example
To demonstrate how the DIME framework functions in practice, let us analyze a typical household scenario. Consider an individual earning $90,000 annually with a spouse and two young children (ages 3 and 6):
| DIME Category | Financial Component Breakdown | Calculated Amount |
|---|---|---|
| Debt (D) | Auto loans ($22,000) + Credit card balances ($8,000) + Final expenses ($15,000) | $45,000 |
| Income (I) | $60,000 essential income replacement x 15 years (until youngest turns 18) | $900,000 |
| Mortgage (M) | Current outstanding principal on primary residence mortgage | $320,000 |
| Education (E) | $100,000 target higher-education fund per child x 2 children | $200,000 |
| Gross Coverage Requirement | $1,465,000 | |
Once you calculate your total gross obligation ($1,465,000 in this scenario), subtract your existing household assets and liquid reserves. If the family holds $80,000 in investment balances and $25,000 in group life insurance provided by an employer, their net personal coverage requirement reduces to $1,360,000.
4. Factoring Inflation, Discount Rates, and Investment Returns
A common pitfall in life insurance planning is treating future financial needs as static numbers. Inflation erodes purchasing power over extended horizons, while capital payouts can be invested in low-risk securities to generate compounding interest over time.
When calculating income replacement needs over a 15- to 25-year timeline, you must apply a net discount rate. The net discount rate represents the differential between the expected return on invested death benefit funds and the anticipated rate of inflation.
For example, if a surviving spouse invests death benefit proceeds in a conservative portfolio yielding 5% per year, and persistent consumer inflation runs at 2.5% per year, the real net discount rate is approximately 2.5%. This allows a smaller initial capital sum to sustain ongoing living expenses than a simple linear calculation suggests.
5. Educational Resource: Expert Video Overview
For a deeper conceptual overview of financial protection strategies and life insurance structure, review this video breakdown:
6. Laddering Policies: Optimizing Cost and Duration
Purchasing a single large 30-year term insurance policy to cover peak debt and dependency years often leads to overpaying in later years. As time passes, your mortgage balance declines, children graduate and enter the workforce, and retirement account balances grow.
The Strategy: Policy Laddering
Instead of securing one $1,500,000 policy for 30 years, you can stack or "ladder" multiple policies with varying term lengths to align directly with decreasing obligations over time:
- Policy A (Short-Term Need): $500,000 policy for 10-year term to cover short-term debts and child rearing during early development years.
- Policy B (Medium-Term Need): $500,000 policy for 20-year term to cover college funding and remaining mortgage balances.
- Policy C (Long-Term Need): $500,000 policy for 30-year term providing ongoing income safety for your spouse into early retirement.
As each policy term naturally expires, your total monthly premium decreases, matching your reduced need for insurance as financial independence increases.
7. Final Strategic Checklist
Before locking in a life insurance policy structure, run through this final tactical checklist:
- Audit existing group policy limits: Employer coverage is convenient, but it is rarely portable if you change jobs or face unexpected health changes.
- Re-evaluate annual life milestones: Major life events (marriage, home purchases, births, business expansions) require an immediate review of your coverage calculations.
- Account for non-earning partners: Stay-at-home parents provide critical household value (childcare, transportation, home management) that would cost tens of thousands of dollars per year to replace professionally.
- Coordinate beneficiary designations: Ensure primary and contingent beneficiary listings align with your overarching estate planning documents and trust structures.