Term vs. Whole Life Insurance: Which Structure Fits Your Timeline?
Navigating the life insurance marketplace requires cutting through dense jargon and conflicting sales tactics. When evaluating life insurance, families quickly encounter a foundational philosophical decision: should they purchase pure risk protection for a set period, or build a permanent financial asset that accumulates cash value over a lifetime?
Selecting the wrong policy structure can cost high-net-worth earners over six figures in opportunity costs over a 30-year span.
The debate between Term Life Insurance and Whole Life Insurance is rarely about which financial instrument is universally superior. Instead, it revolves around capital efficiency, risk capacity, and time horizon. This guide provides an analytical breakdown of how both vehicles perform under real-world market conditions, estate transfers, and liquidity needs.
Understanding Term Life: Pure Risk Protection
Term life insurance operates on pure risk transfer. Much like personal property, auto, or health coverage, you pay an insurance carrier a fixed premium in exchange for an unvarying death benefit across a defined window typically 10, 15, 20, or 30 years.
If the policyholder passes away while the policy is active, the beneficiary receives the full tax-free death benefit. If the term expires while the policyholder remains alive, the contract terminates. There is no accrued cash equity, no surrender value, and no ongoing mortality protection unless extended through expensive conversion riders.
Key Benefits of Term Structures
- Maximum Death Benefit Leverage: Because premium pricing strips away savings mechanisms, term insurance offers the highest protection-to-cost ratio. A healthy 35-year-old can often secure a $1,000,000 20-year term policy for under $45 per month.
- Fixed Overhead Predictability: Level-premium term guarantees your rates will not fluctuate throughout the term duration.
- Targeted Horizon Alignment: Term coverage excels when matched against fixed-term liabilities, such as a 25-year mortgage, debt obligations, or the years required for dependents to reach financial independence.
Whole Life: Permanent Coverage with Cash Equity
Whole life insurance is a permanent financial structure designed to remain active for the policyholder's entire natural life, up to maturity (typically age 100 or 121). Premiums are split between covering actual mortality and administrative costs, and funding a tax-deferred cash value account.
The cash value account within a whole life policy grows based on a guaranteed internal interest rate set by the insurer, alongside non-guaranteed policy dividends awarded by mutual life insurance carriers. Policyholders can borrow against this accumulated balance tax-free, using their capital collateral to fund investments, supplement income, or navigate financial emergencies.
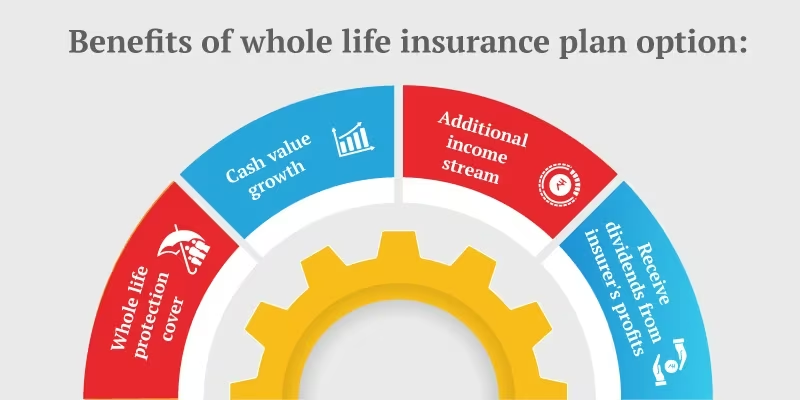
Whole life policies offer guaranteed cash-value equity, but upfront outlay remains significantly higher than term counterparts.
The Structural Cost Trade-Off
Because whole life policies guarantee a payout and maintain an equity component, premium requirements are high often 8 to 12 times higher than an equivalent term policy for the same age and health profile. During the first 5 to 10 years of a whole life contract, a large portion of early payments goes toward insurer commissions and underwriting fees, yielding slow early cash-value accrual.
"Purchasing whole life insurance simply for investment returns often introduces unnecessary fee structures. Its strength lies in tax efficiency, asset protection, and estate liquidity not speculative yield."
Andrew Benny
Side-by-Side Architectural Comparison
To evaluate how these insurance types align with your overarching wealth strategy, review their core structural mechanics side by side:
| Feature Parameter | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Duration of Coverage | Fixed Horizon (10 to 30 years) | Permanent (Lifetime) |
| Initial Monthly Outlay | Low (Pure cost of risk) | High (5x–12x higher) |
| Cash Value Accumulation | None | Guaranteed build-up + Dividends |
| Policy Loans & Liquidity | Unavailable | Available against cash balance |
| Estate Tax Utility | Limited to contract term | High (Irrevocable Life Insurance Trusts) |
| Primary Strategic Role | Income Replacement & Debt Coverage | Estate Planning & Wealth Transfer |
Comprehensive Analysis: Video Breakdown
For a detailed breakdown of the internal rates of return (IRR) between investment strategies and permanent insurance structures, view this objective overview on policy mechanics:
Strategic Asset Allocation Frameworks
Choosing between these two models requires matching financial tools to specific life phases and wealth building strategies.
1. The "Buy Term and Invest the Difference" (BTID) Strategy
The BTID approach remains popular in modern personal finance theory. Under this framework, an investor takes the money saved by purchasing a term policy over a whole life policy and invests it in low-cost index funds or growth assets.
For example, if a whole life policy costs $600 per month and a term policy costs $50, the investor channels the remaining $550 per month into broad market index portfolios. Over 30 years, assuming a typical 7-8% annualized market return, the accumulated liquid asset value frequently outperforms the guaranteed cash value of a whole life policy, while leaving the investor with full control over their investment vehicles.
2. Wealth Preservation and Estate Liquidity Frameworks
For high-net-worth individuals, high-earners who max out qualified retirement plans (401ks, IRAs, Backdoor Roths), or business owners, permanent life insurance serves distinct structural roles:
- Illiquid Asset Liquidity: If an estate consists primarily of real estate or family enterprises, a permanent death benefit provides quick cash to settle federal estate taxes without forcing a fire-sale of properties.
- Tax-Free Asset Transfer: Death benefits pass to beneficiaries free of federal income tax, offering a clean distribution mechanism within complex estate structures.
- Asset Protection Mechanics: In several legal jurisdictions, cash value built inside permanent life policies is sheltered from creditor claims and legal judgments.
Final Recommendation and Execution Path
Selecting life insurance comes down to balancing current cash flow, risk tolerances, and long-term targets:
- Choose Term Life Insurance if: Your priority is protecting your family during high-liability working years, covering debt liabilities, ensuring college funding, or securing maximum income coverage at an efficient price point.
- Choose Whole Life Insurance if: You have built a solid financial foundation, maxed out traditional tax-advantaged accounts, need lifelong coverage for a special-needs dependent, or require permanent tax-free liquidity to handle complex estate distributions.
Work with a fee-only fiduciary advisor to run comparative illustrations. Analyzing actual policy costs, historical carrier dividend records, and projected surrender charges ensures your decision supports your broader financial timeline.