
Renters Insurance Made Simple: Cover the Gaps Your Landlord Leaves
Many renters believe a costly myth. They think the landlord’s insurance protects everyone in the building. This idea is common in apartments, rented houses, and shared condos. A renter may think that if a pipe bursts, the landlord’s insurer will pay. The same goes for a fire from a bad wire. It also goes for a storm that harms the roof. They expect a check for a new laptop, couch, clothes, and home office. This belief is wrong. It leaves many people with no help when a disaster strikes.
The real rules are quite different. A house owner’s policy covers only the their building. It pays for the frame, the walls, the roof, and the appliances the landlord owns. It stops at your front door. Everything you bring inside is your own risk. That includes your clothes and your phone. It also includes costly things like a ring or a custom bike.
A good renters insurance policy fills this gap. It is not just a smart money habit. It is a strong shield against sudden and huge loss. In this article, you will going learn how it works. You will also learn what it costs you if you skip it, and how to choose the right plan.
What Does Renters Insurance Actually Cover?
A renters policy rests on three main parts. They are personal property cover, personal liability cover, and loss of use cover. Loss of use is also called additional living expenses. Let us look at how each part works in real life. This will show you why the cover matters.
1. Personal Property Protection
This part helps when your things are harmed, ruined, or stolen. The cause must be one your policy lists. Insurers call these causes named perils. Most standard renters policies list 16 of them. They include fire, smoke, blasts, vandalism, theft, and wind. They also cover falling objects. Water damage is covered too. It must come from a sudden pipe burst or an appliance that overflows.
There is one more key point. This cover usually works anywhere in the world. Say a thief takes your laptop from your car on a trip. Or say an airline loses your bag. Your policy can still pay you back. Think of the named perils as a list. If the cause of the loss is on the list, the policy can pay. If it is not on the that list, it will not get paid.
2. Personal Liability Coverage
Your things matter. But the liability part of your policy may save you even more. It can spare you from a debt that changes your life. Say a guest trips on a rug in your home and breaks a wrist. Or say you leave a kitchen tap on. The water ruins the ceiling of the flat below. In both cases, the law could hold you to blame. Legal bills can grow fast. Even a small accident can lead to a large bill. Liability cover pays for your legal defense fees. It pays court rulings and medical bills too. It pays up to the limit you pick. Most limits are between $100,000 and $300,000.
3. Additional Living Expenses (Loss of Use)
Now picture a bad fire or a major water leak. Your home is no longer safe to live in. Your lease may pause, but you still need a place to sleep that night. Loss of use cover pays for that need. It can pay for a hotel or a short-term rental. It can pay you for meals that cost more than your actual food budget. It can pay for laundry too. The help lasts while your home is fixed or while you find a new one. This cover means you do not have to pay for two homes at once. It gives you time to recover.
ACV vs. Replacement Cost: Which Policy Type Is Better?
When you set up a policy, you face a big choice. You can pick Actual Cash Value, or ACV. Or you can pick Replacement Cost Value, or RCV. Many renters are upset when they file a claim. The top reason is that they chose the wrong option at the start. So it pays to learn the difference now. An ACV policy takes off money for age and wear. This is called depreciation. Here is an example. You bought a top TV five years ago for $1,200. Today a covered electrical fire destroys it. An ACV payout looks at what the TV is worth now. It counts the age and the wear. The check may be only
$300. That is far too small to buy a new TV of the same kind. You would have to pay the rest from your own pocket. An RCV policy does not count depreciation. The insurer pays what it costs today to buy a brand new item of like quality. Your deductible is taken off first. A deductible is the part you pay yourself. This way you can buy a new item, not just cover its old value.
ACV vs. RCV: Payout Comparison for Renters Insurance
The table below shows how the ACV and RCV types are differ. It uses three common items. Read across each row to see the gap.
| Item | Original Price | Item Age | ACV Payout |
RCV Payout |
| 4K Smart TV | $1,200 | 4 years | $350 | $1,200 |
| Leather Sofa | $2,500 | 6 years | $600 | $2,500 |
| Workstation Laptop | $1,800 | 3 years | $500 | $1,800 |
| Total (before deductible) | $5,500 | – | $1,450 | $5,500 |
RCV amounts are shown at about the original price, as a simple example. Real payouts depend on today’s store prices. An RCV policy often costs 10% to 15% more than an ACV policy. But look at the table. After a total loss, the gap in your payout can reach thousands of dollars. For most people, the given choice is easy. RCV is the smart buy. A small rise in cost each month can save you a lot of money later.
Understanding Coverage Limits and Endorsements
Most renters policies set small limits on costly kinds of items. Your policy may have $50,000 in total cover for your things. Yet some groups of items often have a lower cap. These groups include jewelry, guns, fine art, and collectibles. Business gear used in a home office is often here too. The cap is often just $1,500 to $2,500 for each group. Read the small print in your own policy. Do this before you ever need to file a claim.
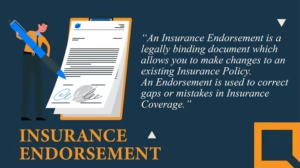
Think about an engagement ring worth $8,000. A basic policy may pay only a small part of that. You would face a big loss gap. You would have to cover the rest yourself. There is a fix. You can add an endorsement for each special item. Insurers often call it a scheduled personal property rider. A rider insures the item for its full appraised value. It often removes the usual deductible for that item. It can also cover an item you lose or misplace by accident. For a special item, the extra fee is often worth it.
Video Guide: Coverage Gaps
A short video here. It shows how cover changes when you move into a rental. It also explains common claims and how policies are built. Watch it to learn more.
What Renters Insurance Does Not Cover
Renters insurance gives wide help. But it does not cover every disaster. It is just as key to know where cover ends. Then you can buy extra policies if you need them. Here are the most common gaps.
- Floods and surface water: A standard policy does not cover damage from rising water. This includes storm surges and rivers that spill If you live in a flood zone or on the ground floor, buy a flood policy. You can get one from the National Flood Insurance Program (NFIP) or from a private insurer. Do not wait for a storm to plan this.
- Earthquakes and earth movement: Quakes, mudslides, and sinkholes are not covered by main This is true for nearly all of them. You need an earthquake add-on or a separate policy.
- Pests and poor upkeep: Renters insurance is for sudden and accidental events. Bed bugs, termites, and mice are not covered. Mold that grows slowly from a leak you never reported is not covered Insurers see these as upkeep issues, not insured events. Tell your landlord about leaks soon so they can fix them.
- Roommate belongings: A policy in your name does not cover a roommate you are not related to. The same is true for their liability. The only way around this is to list them on the policy declaration page. Each roommate may also want their own policy.
How to Value Your Belongings: A Step-by-Step Guide for Renters Insurance
To pick the right limit, do not just guess a round number. Make a full home inventory instead. Keep a written record as you go. These steps will help you avoid too little cover. They will also help you avoid paying for cover you do not need. Follow them one at a time.
- Film each room. Walk through your home with your phone camera. Open closets, drawers, and As you film, say the brand names, the buy dates, and the condition of each item.
- Save your big Scan or store digital copies of receipts for major buys. These include laptops, TVs, nice furniture, and luxury goods. Keep them in safe cloud storage.
- Write down serial numbers. Note the serial number of each costly gadget, appliance, and tool. Claims adjusters can process a claim much faster when the serial numbers are
- Add up the cost. Tally what it would cost to replace all your things. Count clothes, gadgets, kitchen items, furniture, and Most people who live alone find that their things are worth
$20,000 to $40,000 in total. That sum is often far more than they guessed.
A careful inventory keeps your cover in line with what you truly own. Then, if theft, fire, or water damage strikes, your recovery can be smooth and complete. You will also feel safe about your money. Take one hour this week to start your list. Your future self will be glad you did.