
How Much Life Insurance Do You Need?
This article shows how to work out the right amount of life insurance for your family wilh Coverage multipliers. It looks at why a simple rule can fail. Then it explains three better methods and gives a step-by-step example. It ends with ways to save money and a checklist to use before you buy.
1. The Problem with Generic Coverage multipliers
For many years, money advisers have shared one simple rule. The rule says to buy life insurance worth 10 times your yearly pay. Say you earn $80,000 a year. Then you would buy $800,000 of term life insurance. Term insurance is cover that lasts for a set number of years. The rule is easy to use. But it has a big flaw.
The rule leaves out many things that matter. It ignores the debts you owe. It ignores the money and property your family already has. It ignores how many people rely on you. It also ignores interest rates and the way prices rise over many years.
Think about two homes. In the first home, one parent earns all the money. There are three young children, a $400,000 home loan, and no savings that you can spend quickly. In the second home, both parents work. Their home loan is small, and they have large investment accounts. Both earners may make the same yearly pay. Yet they need very different plans to stay safe.
If you buy too little cover, your family may struggle. They could face money trouble in the years when they need help most. If you buy too much, you waste money on high bills. That money could do more good somewhere else. You could put it in savings that are kind to your taxes. You could pay off debt. You could also build a cash fund for emergencies.
2. Advanced Valuation Models Compared for Coverage multipliers
Experts who study risk use three math methods to set a target for life insurance. Each method makes its own guesses about your life. When you know what those guesses are, you can pick the method that fits your family best.
A. The Human Life Value (HLV) Model
This method treats a person as a money asset. Your work can bring in cash for years to come. The method finds out what that future pay is worth in today’s money. This is called the net present value, or NPV. The method counts only the pay that will help your family. So it first takes away your taxes. It also takes away your own living costs and the cost of taking care of yourself. Here is the formula:
HLV Formula:
NPV = SUM [ (Gross Income – Personal Expenses – Taxes) / (1 + r)t ]
In the formula, the letter r is the net discount rate. You find it by taking the return you earn on your investments and subtracting how fast your pay grows. The letter t is the number of years you still plan to work before you retire.
B. The Financial Needs Analysis (DIME Framework)
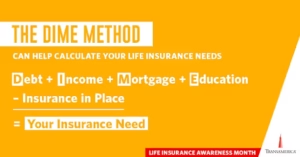
The HLV method looks at how much you could earn. The DIME method looks at what you owe and what your family needs. It breaks the total need into four parts. The name DIME comes from the first letter of each part.
- Debt (D): This is the total of all short-term and mid-term debts, except your home It includes credit card balances and personal credit lines. It also includes car loans, student loans, and unpaid medical bills.
- Income (I): This is the money your family needs to replace your pay for a set That time usually lasts until your youngest child can live on their own. This is often between age 18 and age 22.
- Mortgage (M): This is the full amount you still owe on your home Paying it off gives your family one less worry about where to live.
- Education (E): This is the cost of college for your children in the Keep in mind that college costs have usually risen faster than normal prices.
C. The Capital Retention Method
The last method is called the Capital Retention Method. It is the most careful method of all. Here, your family does not spend the death benefit. The main sum stays whole. It sits in a trust or in a safe mix of investments. Only the yearly gains and dividends are paid out. That income pays for the family’s living costs.
Coverage multipliers Requirement Comparison Across Valuation Models
The simple rule gives the lowest amount. The liability-based DIME method gives more. The perpetual yield method gives the most, because the family never touches the main sum. Each method answers a slightly different question. So it helps to know which one fits your goals.
3. Step-by-Step DIME Calculation Example
Let us see how the DIME method works in real life. Picture a person who earns $90,000 a year. This person has a spouse and two young children. The children are 3 years old and 6 years old.
| DIME Category |
Financial Component Breakdown |
| Debt (D) | Car loans ($22,000) + credit card balances ($8,000) + final costs ($15,000) |
| Income (I) | $60,000 of needed income each year x 15 years (until the youngest child turns 18) |
| Mortgage (M) | The amount still owed on the home loan |
| Education (E) | $100,000 college fund for each child x 2 children |
Let us look at the math in each row. The debt part adds up to $45,000. The income part is $60,000 times 15 years, which is $900,000. The education part is $100,000 times two children, which is $200,000. The total of $1,465,000 also means that the home loan balance is $320,000.
Gross Coverage multipliers Requirement
First, add up all four parts. In this case, the total need is $1,465,000. Next, take away what the family already has. The family has $80,000 in investments. It also has $25,000 in life insurance from an employer. After you subtract both, the family needs $1,360,000 of cover of its own
4. Factoring Inflation, Discount Rates, and Investment Returns
One common mistake in life insurance planning is to treat future needs as fixed numbers. But prices rise over time. This is called inflation. It means your money buys less each year. On the other hand, the death benefit can be invested in low-risk assets. Those assets can grow and earn interest over time.
Suppose you plan for income needs over 15 to 25 years. Then you should use a net discount rate. This rate is the gap between two numbers. The first is the return you expect on the invested death benefit. The second is the rate of inflation you expect.
Here is an example. A surviving spouse puts the payout into a safe mix of investments. It earns 5% each year. Prices keep rising by 2.5% each year. The real net discount rate is then about 2.5%. This means the family can start with a smaller lump sum than a plain, straight-line sum would suggest. The money can still cover their living costs for many years. So do not use static numbers. Let inflation and investment returns shape your final answer.
5. Educational Resource: Expert Video Overview
6. Laddering Policies: Optimizing Cost and Duration
Many people buy one large term policy that lasts 30 years. It Coverage multipliers is one with the years and the most debt and the most need. But this often means you pay too much in the later years. Over time, your home loan shrinks. Your children finish school and start to work. Your retirement savings grow.
The Strategy: Policy Laddering. Instead of buying one $1,500,000 policy for 30 years, you can stack several policies. Each policy has a different length. This is called laddering. The stack matches your need for cover, which falls over time.
- Policy A (Short-Term Need): This is a $500,000 policy for a 10-year It covers short-term debts. It also covers the cost of raising your children in their early years.
- Policy B (Medium-Term Need): This is a $500,000 policy for a 20-year It covers college costs and what is left of your home loan.
- Policy C (Long-Term Need): This is a $500,000 policy for a 30-year It gives your spouse steady income and safety into early retirement.
Each policy ends when its term runs out. When that happens, your monthly bill goes down. This fits your life well. You need less cover as you gain more money freedom.
7. Final Strategic Checklist for Coverage multipliers
Before you lock in a life insurance plan, go through this last list of steps for Coverage multipliers
- Check your group policy Cover from your employer is easy to get. But you often cannot take it with you if you change jobs. You may also lose it if your health changes without warning.
- Review your plan after big life Marriage, buying a home, having a baby, or growing a business all count. Each one calls for a fresh look at your numbers right away.
- Count partners who do not earn a A parent who stays home adds great value. They care for the children, drive them around, and run the home. Paying someone else to do this work could cost tens of thousands of dollars each year.
- Match your beneficiary choices. Make sure your main and backup beneficiaries agree with your estate They should also agree with any trusts you have set up.
Take your time with these steps. A little care now can protect your family for many years. It can also keep your monthly bills fair as your life changes.